Scotland
 UK
 Ireland
 London
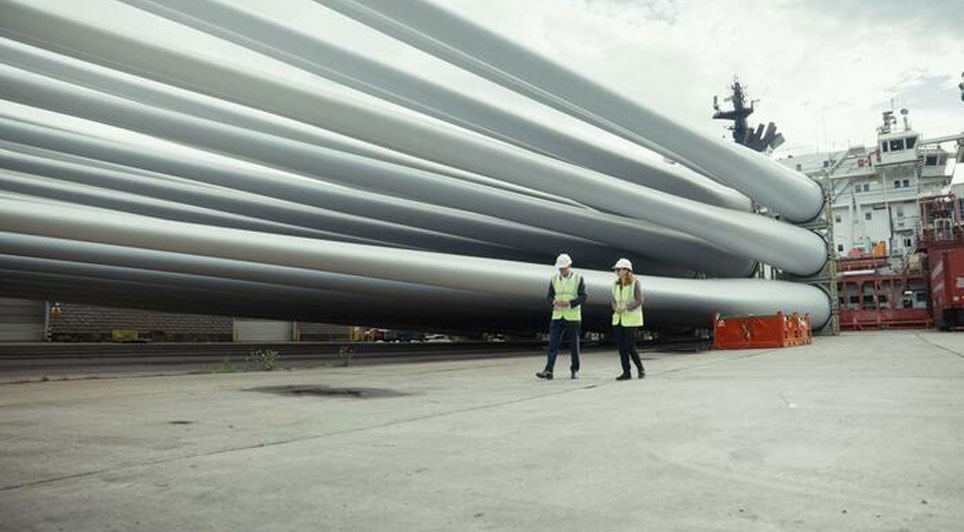
Scottish Renewables chief Angela Hepworth warns that rising costs, grid charges and planning delays threaten a 23GW floating wind pipeline unless clear, coordinated action restores investor confidence.
Four years ago, Scotland set out bold intentions for floating offshore wind. The ScotWind and INTOG leasing rounds drew interest from across the globe and catalysed activity in our waters, ports and supply chain.
Scotland now has a floating offshore wind pipeline of more than 23GW. Around 14GW across eight projects has entered the planning system, while three further projects have secured consent.
Yet the sector has reached a critical juncture. Since those leases were awarded, costs have climbed and the operating environment has become tougher. Investors are weighing the pace of consenting and the implications of changes to grid connections and long-term network planning. Decisions in these areas must provide the certainty to unlock capital.
Confidence is essential because Scotland's opportunity is not assured. Crown Estate Scotland estimates the 10 floating offshore wind projects in ScotWind could spend £18.4 billion in the Scottish supply chain over their lifetimes, rising to £25.9 billion across the UK. Realising that potential means moving further and faster.
That is why Andy Burnham's focus on reindustrialisation and good growth matters. Floating offshore wind can turn those ambitions into lasting opportunities for coastal and industrial communities, but only if political and commercial backing for the sector remains steadfast.
Support must also reflect the pressures facing households and businesses. Domestic energy costs have doubled since 2017, with around 70% of the increase attributed to inflation and rising global commodity prices. People need help now and a future in which global shocks have less impact on bills at home.
This strengthens, rather than weakens, the case for investment. Floating offshore wind will not cut bills overnight, but it can be a key pillar of a future energy system. Bringing costs down starts with building and learning from stepping-stone projects so the sector can scale towards commercial deployment.
A steady programme of larger schemes must then follow. This will run beyond 2030, so ports and suppliers require a clear timetable to justify investment in construction, operations and maintenance. Affordability and industrial growth also depend on tackling risks developers cannot control.
Transmission charging is a prime example. Developers must budget for what they will pay to use the grid, yet charges are rising and increasingly hard to predict. In the North of Scotland, where much of our offshore wind resource sits, these charges are expected to double by 2030, with £2.9 billion of unforeseen costs since 2015. Developers will price in that risk or think twice about building.
The forthcoming Strategic Spatial Energy Plan is another decisive test of confidence. Scotland has progressed projects and developed port capacity at Ardersier, Montrose, Kishorn and Leith. Any plan that casts doubt on this pipeline and the local activity it supports would send a damaging signal just as investment needs to accelerate.
Timing matters for the wider North Sea, too. If good growth is to reach every postcode, we must bridge the gap between the industries sustaining offshore communities today and the projects that can sustain them in future. Skilled workers and specialist suppliers cannot wait indefinitely. Without clear signals soon, expertise and investment could drift elsewhere and be hard to recover.
The barriers are well known: grid access, the pace of consenting, supply chain readiness and viable routes to market. No single policy can remove them all, but letting them compound only weakens the overall investment case.
Government and industry must act together to build confidence, reduce costs and keep Scotland's offshore expertise at work. Floating offshore wind can strengthen energy security, help deliver more affordable electricity and create good jobs in places that have powered Britain for generations.
Scotland has the projects and the know-how, but its first-mover chance is time-bound. Backing the sector now means taking the decisions that will carry it through its early years. Without that resolve, investment, jobs and hard-won capability will go elsewhere.